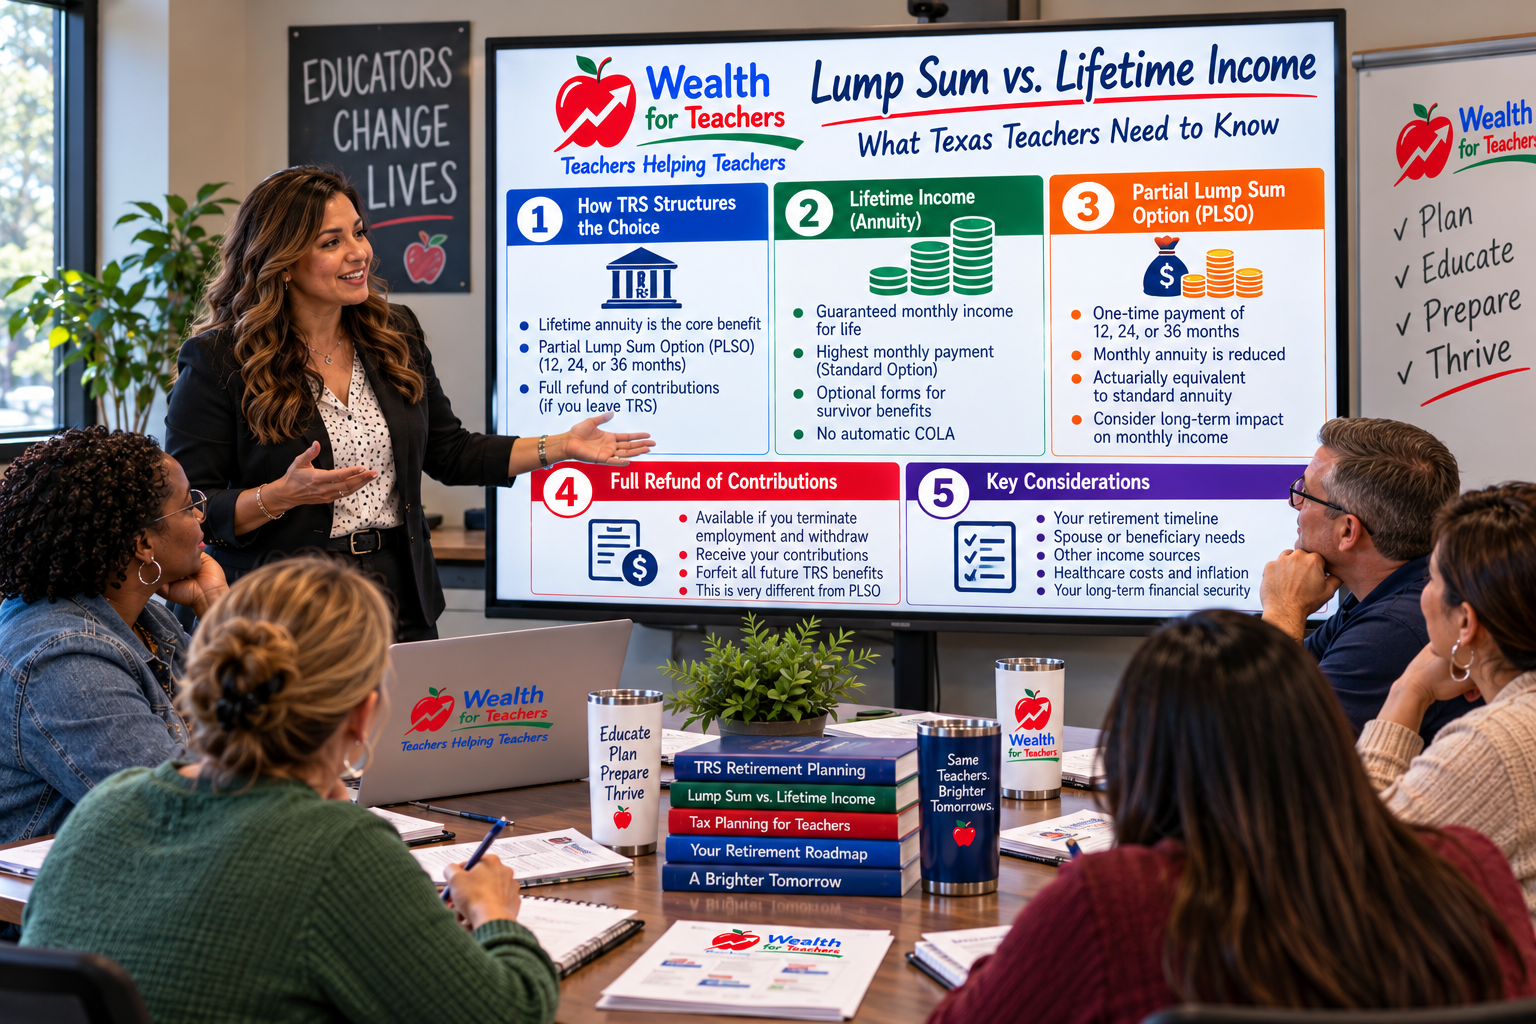
Should Teachers Take Lump Sum or Lifetime Income?
Choosing the wrong option can impact your long-term security.
Professional guidance can prevent costly mistakes
Most Texas teachers spend decades building toward a TRS pension, only to find that the final decisions surrounding that pension are far more complex than expected. Choosing the wrong payment option, retiring one year too early, or misreading eligibility rules can permanently reduce a benefit that took thirty years to earn.
Texas teachers can also run a full pension estimate using the Texas Teacher Retirement Calculator to better understand their retirement outlook.
The question of whether to hire a retirement advisor for teachers is not about whether you are capable of reading the TRS handbook. It is about whether the stakes are high enough to warrant an independent review before you make decisions you cannot reverse.
For most Texas teachers, those stakes are significant. Your pension, your health coverage through TRS-Care, your Social Security eligibility, and your supplemental savings all interact in ways that are easy to misread — especially when you are making these decisions for the first time and under a deadline.
Start with a solid foundation by reviewing the Texas Teacher Retirement Planning Guide, which covers the core decisions Texas teachers face at every stage of their career.
This article is designed to help you decide when professional guidance is worth seeking, what it should focus on, and what happens when key decisions are made without it.
Most retirement plans look reasonable on paper. The problem is that very few teachers ever subject their plan to real-world pressure before they lock in their decisions. A pension amount that seems sufficient at 58 may look very different at 75 when health costs have risen, supplemental savings have been drawn down, and there is no mechanism to adjust.
Use the TRS calculator to estimate your pension and identify potential income gaps.
A plan that has never been tested against inflation, a market decline, or an unexpected healthcare expense is not truly a plan. It is an assumption. A retirement specialist exists, in large part, to replace untested assumptions with verified projections — before those decisions become permanent. You can also explore how to stress-test your retirement plan for worst-case scenarios to understand what that process looks like in practice.
A retirement specialist who works with teachers is not simply a financial advisor who also happens to know what TRS stands for. The difference is depth of focus. A true teacher retirement specialist understands the TRS benefit formula, the tier structure, the payment options available at retirement, the rules surrounding TRS-Care health coverage, and how a teacher’s overall income picture — including any Social Security eligibility — fits together.
Here is what meaningful guidance typically includes:
The value is not in the individual tasks. It is in how all of those pieces are evaluated together, by someone who understands how they interact specifically within the Texas TRS environment.
Texas TRS uses a straightforward benefit formula: your annual pension equals your years of service multiplied by 2.3%, multiplied by your final average salary.
As an example, a teacher with 28 years of service and a final average salary of $62,000 would receive an annual pension of approximately $39,928 (28 × 0.023 × $62,000). That number is fixed for life. The decisions surrounding how and when you claim that benefit, however, are not simple.
Several decisions carry outsized risk:
Understanding whether to retire earlier or later as a Texas teacher is one of the most consequential financial decisions you will make, and it is worth analyzing before submitting any paperwork.
Texas public school teachers do not pay into Social Security through their TRS-covered employment. However, many teachers have Social Security-covered work history — from summer jobs, part-time employment, a second career, or a spouse’s record.
For years, two federal rules — the Windfall Elimination Provision (WEP) and the Government Pension Offset (GPO) — reduced or eliminated Social Security benefits for public pension recipients. That changed with the passage of the Social Security Fairness Act.
The Social Security Fairness Act, HR 82, was signed into law on January 5, 2025. The Act eliminates the reduction of Social Security benefits for those entitled to public pensions from work not covered by Social Security. December 2023 is the last month that WEP and GPO applied. Those rules no longer apply to benefits payable for January 2024 and later.
This is a meaningful change for many Texas teachers. If you previously assumed Social Security would not be worth claiming because of WEP or GPO, that assumption may no longer be accurate. A retirement specialist familiar with the current rules can help you model whether Social Security benefits are now available to you or your spouse, and how to time that claim relative to your TRS retirement date.
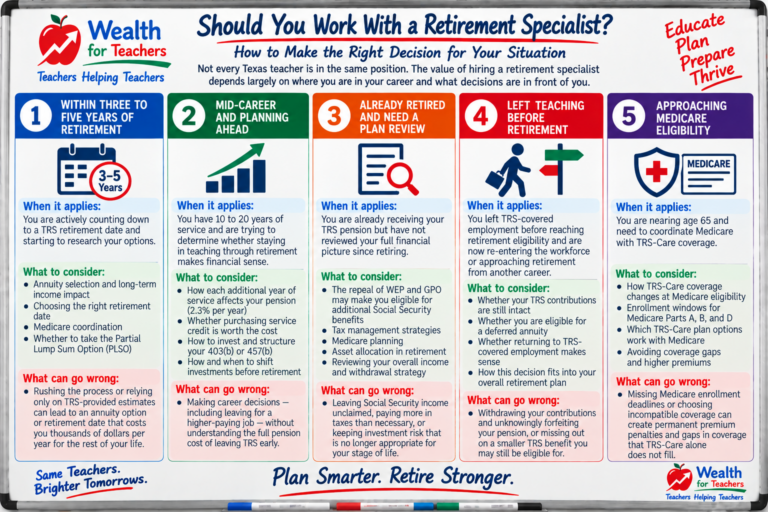
Not every Texas teacher is in the same position. The value of hiring a retirement specialist depends largely on where you are in your career and what decisions are immediately in front of you.
When it applies: You are actively counting down to a TRS retirement date and starting to research your options.
What to consider: This window is when the most consequential decisions are made. Annuity selection, timing, Medicare coordination, and whether to take the Partial Lump Sum Option (PLSO) all need to be analyzed before you submit your retirement application.
What can go wrong: Teachers who rush this phase — or rely solely on TRS-provided estimates without independent analysis — sometimes choose an annuity option or retirement date that costs them thousands of dollars per year in lost income for the rest of their life.
When it applies: You have 10 to 20 years of service and are trying to determine whether staying in teaching through retirement makes financial sense.
What to consider: A mid-career review can help you understand how each additional year of service affects your pension, whether purchasing service credit is worth the cost, and how your supplemental retirement accounts should be invested and structured. Learning about how and when to shift investments before retirement is relevant here — moving too conservatively too early can erode the purchasing power you will need decades later.
What can go wrong: Without a clear projection of what your pension will actually be, mid-career teachers often make career decisions — including whether to take a higher-paying private-sector job — without understanding the full pension cost of leaving TRS early.
When it applies: You are already receiving your TRS pension but have not reviewed your full financial picture since retiring.
What to consider: The repeal of WEP and GPO means some retired teachers now have unclaimed Social Security benefits available. Tax management, Medicare planning, and asset allocation in retirement are all areas where guidance can add value even after the pension is locked in.
What can go wrong: Retired teachers sometimes leave Social Security income unclaimed, pay more in taxes than necessary, or carry investment risk in their supplemental accounts that is no longer appropriate for their stage of life.
When it applies: You left TRS-covered employment before reaching retirement eligibility and are now re-entering the workforce or approaching retirement from another career.
What to consider: Whether your TRS contributions are still intact, whether you are eligible for a deferred annuity, and whether returning to TRS-covered employment makes sense are all questions with significant financial implications.
What can go wrong: Some teachers who left TRS-covered employment withdrew their contributions and unknowingly forfeited their pension. Others may be eligible for a smaller TRS benefit they are not aware of. A specialist can help clarify what, if anything, is still available.
When it applies: You are nearing age 65 and need to coordinate Medicare with TRS-Care coverage.
What to consider: TRS-Care coverage for retirees changes at Medicare eligibility. Enrolling at the wrong time or in the wrong plan can result in coverage gaps or higher premiums. The coordination of TRS-Care with Medicare Parts A, B, and D requires attention to enrollment windows and plan options.
What can go wrong: Missing Medicare enrollment deadlines or choosing incompatible coverage can create permanent premium penalties and gaps in coverage that TRS-Care alone does not fill.
Use these questions to identify gaps in your current retirement planning. If you cannot answer one or more of them with confidence, that is a signal that outside guidance may be worth pursuing.
If you answered “no” or “I’m not sure” to two or more of these questions, you are carrying unresolved risk into decisions that are either already in front of you or approaching quickly. This is precisely the gap a qualified retirement specialist is designed to close. It is also worth understanding what happens if inflation stays high in retirement, since a fixed pension can lose purchasing power over time in ways that are easy to underestimate.
If you have been relying on informal conversations, general financial advice, or TRS-provided estimates alone, here is a more structured approach:
One of the most important things to understand about retirement planning for Texas teachers is that many of the costliest mistakes are invisible until it is too late to correct them. A teacher who retired at the wrong time, selected the wrong annuity option, or missed a Medicare enrollment window does not always realize the financial impact immediately. These gaps surface months or years later — when adjusting course is no longer an option.
This is not a hypothetical concern. TRS eligibility rules are layered across multiple membership tiers, each with different requirements for normal-age and early-age retirement. The Social Security landscape for teachers has recently shifted in ways that many current and retired teachers have not yet incorporated into their planning. Supplemental accounts may be invested in ways that reflect a strategy from ten years ago rather than the retirement that is now approaching.
The danger is not that teachers fail to plan. Most do plan. The danger is that the assumptions built into that plan are never pressure-tested before the major decisions are locked in. By the time a gap becomes visible, the retirement date has already been set, the annuity option has already been selected, and the opportunity to make a different choice has passed.
Getting those decisions right the first time requires knowing what you do not know — and having someone who can identify it before it costs you.
TRS provides benefit estimates, eligibility information, and educational resources through MyTRS and the TRS Benefits Handbook. What TRS does not provide is personalized financial planning that accounts for your complete financial picture — including Social Security, supplemental accounts, taxes, healthcare costs, and survivor needs. That is the gap a retirement specialist fills.
The Texas TRS formula is straightforward: Annual Pension = Years of Service × 2.3% × Final Average Salary. For example, with a final average salary of $50,000 and 22 years of service credit, the gross annual annuity is calculated as 2.3% × $50,000 × 22 = $25,300. The final average salary used in the calculation depends on your membership tier — grandfathered members use the average of their highest three annual salaries, while non-grandfathered members use the average of their highest five annual salaries.
It depends on whether you have qualifying work history outside of TRS-covered employment. Texas public school positions do not contribute to Social Security, but work in other covered jobs does. People who benefit from the Social Security Fairness Act include some teachers, firefighters, and police officers in many states. The repeal of WEP and GPO for benefits payable beginning January 2024 means some teachers may now be eligible for Social Security benefits they previously assumed would be reduced or eliminated.
For most Texas teachers, meaningful guidance is most valuable in the three to five years before retirement — when annuity options, retirement dates, and healthcare transitions are actively being decided. However, a mid-career review can also surface important information about service credit, supplemental savings, and long-term projections that change how you manage the years leading up to retirement.
Look for demonstrated familiarity with Texas TRS specifically — including the tier system, annuity options, TRS-Care, and the interaction between TRS income and Social Security. A specialist who works primarily with educators will understand the nuances that a general financial advisor may overlook. Ask directly: how many Texas public school teachers do you work with, and can you walk me through the TRS annuity options?
The Rule of 80 means that the combined age and years of service credit equal at least 80. Normal age retirement eligibility requirements vary by membership tier. For example, members who first became members or returned to membership on or after September 1, 2014 — or who had less than five years of service credit on August 31, 2014 — must meet either age 65 with five or more years of service credit, or at least age 62 while meeting the Rule of 80 with at least five years of service credit. Members in other tiers may have different normal age eligibility requirements. Confirming which tier applies to you is an essential first step.
Retirement planning for Texas teachers involves a specific set of rules, deadlines, and irreversible decisions that general financial guidance was not designed to address. The teachers who fare best in retirement are not necessarily those with the largest pensions — they are the ones who understood their options fully before making any of them permanent. That kind of informed decision-making is what a qualified retirement advisor for teachers is positioned to support.
Use the TRS calculator to estimate your pension and identify potential income gaps.