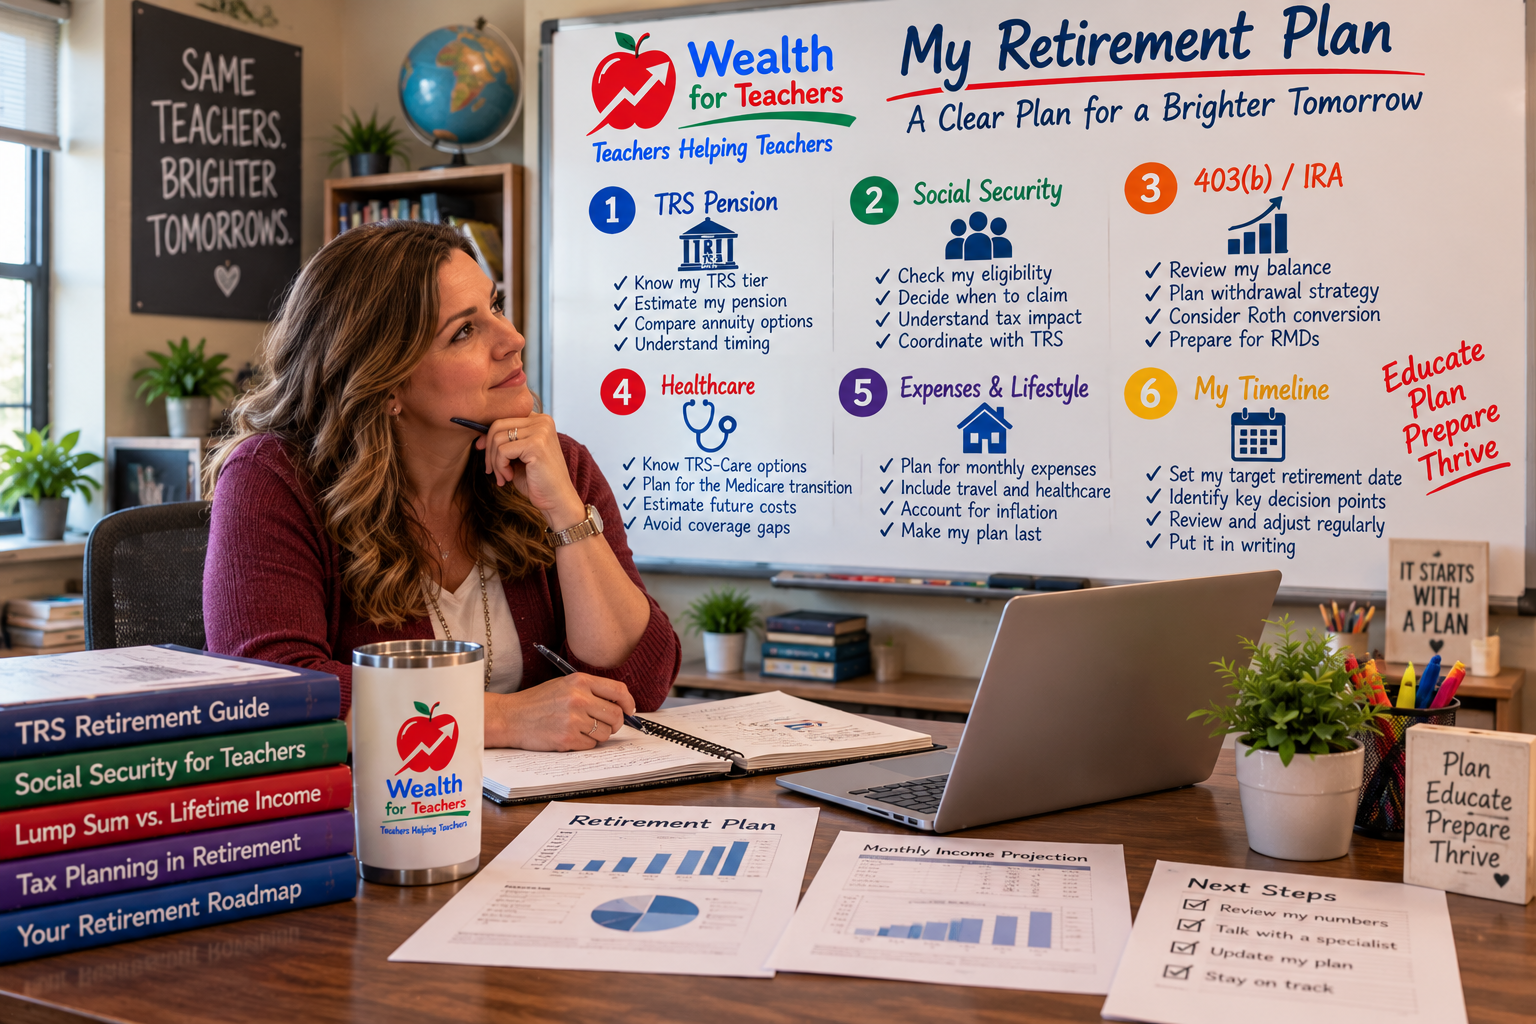
Should Teachers Create a Written Retirement Plan?
A written plan provides clarity and direction. Here’s why it matters.
Planning doesn’t stop at retirement—it changes.
` wrapper preserved.
Most retirement plans are built around a single goal: accumulate enough money to retire. Texas teachers spend decades contributing to TRS, building service credit, and watching their pension estimate grow. That part of the plan usually works.
Texas teachers can also run a full pension estimate using the Texas Teacher Retirement Calculator to better understand their retirement outlook.
What fails is what comes next.
The moment income begins, the rules change entirely. A plan that was designed to grow assets now has to produce reliable income — month after month, for potentially 25 or 30 years — without running short, without triggering unnecessary taxes, and without locking in decisions that cannot easily be undone. Retirement income failure for teachers does not usually happen all at once. It happens gradually, through small misalignments between what a teacher assumed would work and what the real-world income phase actually demands.
Understanding what goes wrong — and why — is the first practical step toward protecting what you have spent a career building. For a broader foundation, start with the Texas Teacher Retirement Planning Guide.
The most reliable way to identify a gap in a retirement plan is to run it forward under real-world conditions — actual income needs, actual tax exposure, actual spending changes over time. Most teachers never do this. The plan stays in the accumulation phase: contribute, grow, repeat. No one stress-tests it against 20 years of withdrawals, a health event in year three, or a market loss in the first year of retirement. When those things happen — and they do — the plan reveals its weaknesses for the first time, often when changing course is most expensive.
Use the TRS calculator to estimate your pension and identify potential income gaps.
During a teaching career, every financial decision is oriented in one direction: forward. You contribute to TRS. You may add a 403(b) or 457 plan. You build equity, reduce debt, and watch your retirement picture improve each year. The math rewards patience and consistency.
Retirement income works differently. Once you retire, every dollar you spend reduces the base from which future income can come. Market losses early in retirement have a magnified impact compared to identical losses during the accumulation years — a dynamic often called sequence-of-returns risk. A Texas teacher who retires into a difficult market environment may face a very different outcome than one who retires into a favorable one, even if both had the same account balance on day one.
The shift from accumulation to income also changes what a “good” investment looks like. During your working years, volatility is tolerable because time allows recovery. In retirement, a sharp decline in a supplemental account — at the same time you are drawing from it — can permanently impair income capacity in ways that cannot be reversed by simply waiting for the market to recover.
Understanding how asset allocation changes for teachers in retirement is essential before making any distribution decisions from supplemental accounts.
The Texas TRS pension is a defined-benefit plan. Your monthly benefit is calculated using a straightforward formula:
Annual Pension = 2.3% × Years of Service Credit × Final Average Salary
For a teacher with 30 years of service and a final average salary of $62,000, that produces an annual pension of approximately $42,780, or roughly $3,565 per month. That is a meaningful income — but it is fixed at retirement.
There are no automatic increases to your annuity once you have retired. Your TRS pension is not automatically adjusted for inflation. That means a pension that covers your expenses comfortably in the first year of retirement may cover noticeably less in year ten. Although your pension may be enough to cover your expenses when you first retire, over time, your monthly annuity purchasing power will decrease.
This is why supplemental savings matter — not just as a backup, but as a structured income source designed to fill specific gaps. Personal savings such as a 403(b), 457, or IRA play an important part in your financial security and can supplement your TRS pension at retirement.
The pension also does not cover the tax layer. TRS annuity payments are generally taxable as ordinary income. If you also have distributions from a traditional 403(b) or traditional IRA, those are taxable too. Coordinating these sources poorly can push a retired teacher into a higher bracket than necessary — not through carelessness, but simply through a lack of planning around distribution sequencing.
Inflation is a persistent threat that many teachers underestimate at the planning stage. If you want to understand how rising prices affect long-term purchasing power, see what happens if inflation stays high in retirement.
Approximately 96% of public school employees do not pay into the Social Security system. For most Texas teachers, that means no Social Security retirement benefit based on their teaching career. However, some teachers have Social Security-covered work history from prior employment, a second job, or a spouse’s record.
For those teachers, the planning landscape changed significantly. Starting in January 2024, Social Security benefits are no longer reduced or eliminated if you receive a retirement or disability pension from work not covered by Social Security. This change is due to the Social Security Fairness Act of 2023, which was signed into law on January 5, 2025, and repealed the Windfall Elimination Provision (WEP) and the Government Pension Offset (GPO).
This is a material change for any Texas teacher who also qualifies for Social Security. If you previously assumed your Social Security benefit would be reduced or eliminated because of your TRS pension, that assumption no longer applies to benefits payable beginning January 2024. If you have not revisited your Social Security picture since this change took effect, it may be worth doing so.
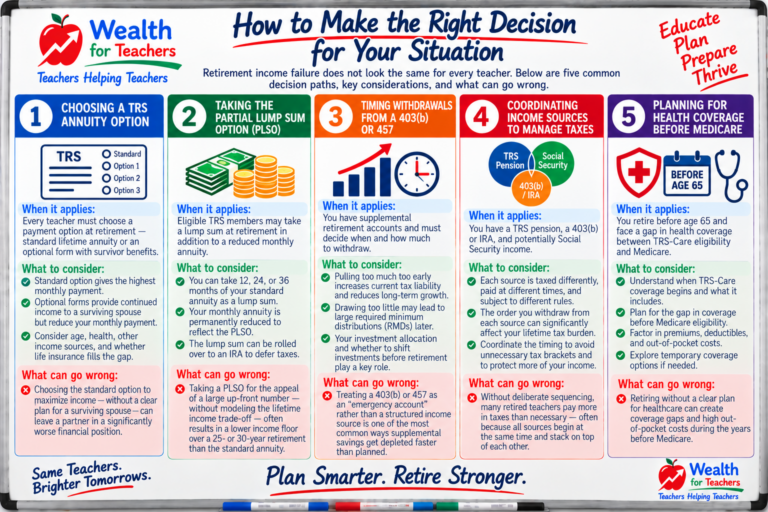
Retirement income failure does not look the same for every teacher. The path that creates risk for one retiree may not apply to another. Below are five decision paths Texas teachers commonly face, along with the key considerations and what can go wrong when the decision is handled without careful analysis.
When it applies: Every teacher must choose a payment option at retirement — standard lifetime annuity, or one of several optional forms that provide survivor benefits.
What to consider: The standard option maximizes your monthly payment but provides nothing to a surviving spouse or beneficiary after your death. Optional forms reduce your monthly payment in exchange for continued income to a survivor. The “right” choice depends on the age and health of both you and your spouse, other income sources your spouse has, and whether life insurance fills the gap.
What can go wrong: Familiarizing yourself with the different annuity payment options available to you at retirement is important so you know which option will work best for you. Choosing the standard option to maximize income — without a clear plan for a surviving spouse — can leave a partner in a significantly worse financial position.
When it applies: Eligible TRS members may elect to take a lump sum at retirement in addition to a reduced monthly annuity.
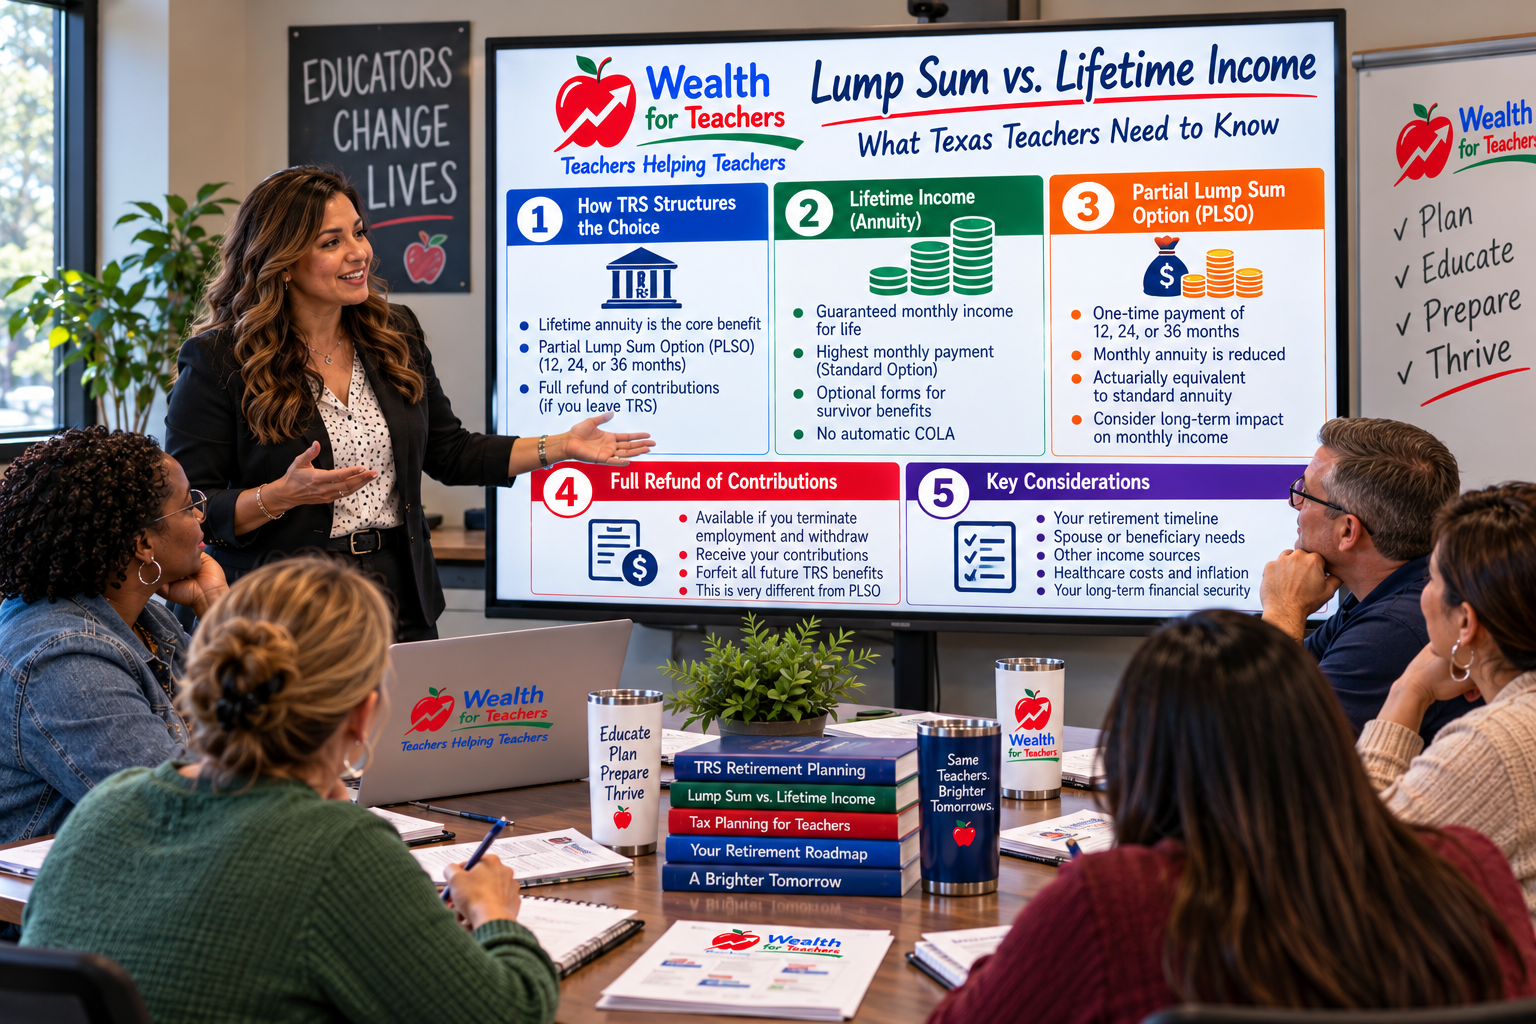
What to consider: Eligible members may select a PLSO equal to 12, 24, or 36 months of a standard service retirement annuity. When a PLSO is selected, the member’s monthly annuity is reduced to reflect the PLSO distribution, and that reduced annuity continues throughout the life of the member. The lump sum can be rolled over to an IRA to defer taxes, but it permanently lowers your monthly income.
What can go wrong: Taking a PLSO for the appeal of a large up-front number — without modeling the lifetime income trade-off — often results in a lower income floor over a 25- or 30-year retirement than the standard annuity would have provided.
When it applies: Teachers with supplemental accounts must decide when and how much to draw from those accounts.
What to consider: Pulling too much too early increases current tax liability and reduces the account’s ability to compound over time. Drawing too little may leave you with large required minimum distributions later that push you into a higher tax bracket. Thinking carefully about whether to shift investments before retirement is part of setting up this strategy correctly.
What can go wrong: Treating a 403(b) as an emergency account rather than a structured income source is one of the most common ways supplemental savings get depleted faster than planned.
When it applies: Teachers with a TRS pension, a 403(b) or IRA, and potentially Social Security income face a multi-source tax coordination problem.
What to consider: Each source is taxed differently, paid at different times, and subject to different rules. The order in which you draw from each source can significantly affect your lifetime tax burden.
What can go wrong: Without deliberate sequencing, many retired teachers pay more in taxes than necessary — often because all sources begin at the same time and stack on top of each other.
When it applies: Teachers who retire before age 65 face a gap in health coverage between TRS-Care eligibility and Medicare.
What to consider: TRS-Care is the health benefits program for eligible TRS retirees, but premiums, coverage levels, and eligibility rules are subject to change. Teachers who retire early need to confirm their specific TRS-Care eligibility and budget for health costs that may be higher than expected before Medicare kicks in at 65.
What can go wrong: Underestimating health care costs in the early retirement years is one of the fastest ways to draw down supplemental savings ahead of schedule, disrupting the entire income plan.
Rather than treating retirement as a finish line, treat it as a transition that requires a different kind of planning. Here is what that looks like in practice:
Use these five questions to identify where gaps or uncertainties may exist in your current retirement plan:
Experts say you will need 80–90% of your pre-retirement income to maintain your current standard of living. You could need more or less than that depending on your lifestyle and factors such as taxes or medical bills. For many Texas teachers, the TRS pension covers a substantial portion of that — but not always all of it, particularly when accounting for inflation over a long retirement.
When a PLSO is selected, the member’s monthly annuity is reduced to reflect the PLSO distribution, and the reduced annuity continues throughout the life of the member. This is a permanent reduction — not a temporary one.
It no longer does for most teachers, thanks to the Social Security Fairness Act. Starting in January 2024, Social Security benefits are no longer reduced or eliminated if you receive a retirement or disability pension from work not covered by Social Security. If you have a Social Security-covered work history and previously assumed your benefit would be offset by your TRS pension, that rule no longer applies to benefits payable from January 2024 forward.
There is no single right answer — it depends on your tax situation, your pension amount, your other income, and your health care costs. The key principle is that the timing and amount of 403(b) withdrawals should be driven by a deliberate income strategy, not by short-term spending needs or a default assumption that you should wait as long as possible.
Some decisions made at retirement are difficult to reverse — particularly the annuity option and any PLSO election. However, distribution strategy from supplemental accounts, tax withholding from TRS, and investment allocation within those accounts can typically be adjusted. The earlier a gap is identified after retirement, the more options remain available.
One of the most uncomfortable realities of retirement planning is that its most consequential decisions — annuity option selection, PLSO election, retirement date — are made before you have had a single day of experience actually living on a retirement income. You are choosing based on projections, estimates, and assumptions. If those assumptions are wrong, the error often does not surface until the plan has been in motion long enough that reversing course is either impossible or very expensive.
A teacher who retires and later discovers that her income does not keep pace with rising expenses has limited options. A teacher who discovers he underestimated his tax burden in retirement faces that cost every year going forward. One who took the maximum PLSO for the appeal of a large lump sum may realize only later that the reduced monthly annuity creates a shortfall that supplemental savings cannot reliably fill over a 25-year horizon.
The purpose of testing assumptions before retirement is not pessimism — it is precision. A retirement income plan that has been stress-tested against real-world conditions gives you a far better chance of staying on track than one that looked solid on paper but was never challenged. Understanding the risks, running the numbers honestly, and identifying the gaps while you still have time to address them is what separates a plan that holds from one that quietly fails.
Retirement income failure for teachers is almost never the result of one dramatic mistake. It is the result of a plan that was never fully adapted to the demands of the income phase — and a transition that deserved more preparation than it received.
Use the TRS calculator to estimate your pension and identify potential income gaps.