The Asset Allocation Mistake That Can Derail a Texas Teacher’s Retirement Income
Most Texas teachers spend decades focused on one goal: reaching retirement eligibility. What happens after that — specifically how you invest and draw from what you’ve saved — rarely gets the same attention. That gap is where real financial damage occurs.
Texas teachers can also run a full pension estimate using the Texas Teacher Retirement Calculator to better understand their retirement outlook.
The question of asset allocation for retired teachers is not simply about stocks versus bonds. It is about building an investment structure that aligns with the income you actually need, the pension income you already have, and the risks that don’t disappear when you stop working — they shift.
If you haven’t already reviewed the full picture of your post-career finances, start with the Texas Teacher Retirement Planning Guide, which covers the decisions that shape how much your TRS pension can actually do for you.
This article explains how asset allocation should change once you retire, why the standard pre-retirement playbook no longer applies, and what specific decisions Texas TRS retirees face that most generic retirement advice ignores.
Table of Contents
- Why Most Retirement Plans Fail Under Real-World Conditions
- What Changes About Asset Allocation When You Retire
- How Your TRS Pension Changes the Equation
- The Risks That Actually Matter in Retirement
- Aligning Your Portfolio to Your Income Needs
- How to Make the Right Decision for Your Situation
- What to Do Instead
- Quick Self-Check Before You Move Forward
- Common Questions Texas Teachers Ask
- Why Most Teachers Don’t Discover Gaps Until It’s Too Late
- Get Your TRS Analysis
Why Most Retirement Plans Fail Under Real-World Conditions
A retirement plan that looks solid on paper can unravel quickly once it faces actual withdrawals, actual market volatility, and actual inflation. The problem is not that teachers fail to plan — it’s that most plans are built around assumptions that are never stress-tested. A 6% return assumption, a static withdrawal rate, or a “set it and forget it” portfolio mix can all look fine in a spreadsheet and collapse within a decade of retirement.
Run Your Free Texas Teacher Retirement Analysis
Use the TRS calculator to estimate your pension and identify potential income gaps.
The plan you had while accumulating savings is not the plan you need while spending them. These are fundamentally different phases that require fundamentally different thinking.
What Changes About Asset Allocation When You Retire
During your working years, asset allocation is primarily about growth. Time is on your side. A market downturn in year three of teaching is an inconvenience. A market downturn in year three of retirement can be genuinely damaging — a concept known as sequence-of-returns risk.
When you are drawing income from a portfolio, losses early in retirement are far more destructive than losses later. This is because you are selling assets at depressed prices to fund living expenses, which reduces the number of shares available to recover when markets rebound. A retired teacher who experiences a significant drawdown in the first few years of retirement may never fully recover — even if markets eventually do.
This is why asset allocation for retired teachers requires a structural shift — not just a minor adjustment to what you held during your career.
The shift typically involves:
- Reducing exposure to high-volatility growth assets
- Increasing holdings in income-generating, lower-volatility assets
- Building a short-term cash or near-cash buffer to avoid forced selling in down markets
- Aligning the portfolio to cover specific income gaps, not just general wealth accumulation
To understand how long your savings need to stretch, see How Long Will Your Retirement Savings Last as a Teacher?
How Your TRS Pension Changes the Equation
Here is where Texas teachers have a meaningful structural advantage — and where many still make costly mistakes.
Upon retirement, TRS members receive a monthly annuity for life. There are no automatic increases to that annuity once you have retired, and the pension is not automatically adjusted for inflation.
Your TRS pension is calculated using a 2.3% multiplier for each year of credited service, applied to your final average salary. The averaging period used to determine your final average salary depends on your membership tier: the highest three annual salaries for grandfathered members, or the highest five annual salaries for non-grandfathered members. Confirm your tier through your annual TRS statement or the MyTRS portal.
Annual Pension = (Years of Service × 0.023) × Final Average Salary
For example, a teacher with 30 years of service and a final average salary of $58,000 would receive an annual pension of approximately $40,020 — or about $3,335 per month. That is a guaranteed lifetime income stream that never depends on market performance.
That guaranteed income changes how you should think about your portfolio. A teacher with a TRS pension covering most essential living expenses does not need their investment portfolio to generate aggressive returns. The portfolio’s job shifts from “grow as much as possible” to “fill specific income gaps and preserve purchasing power over time.”
Personal savings such as a 403(b), 457, or IRA play an important part in your financial security and can supplement your TRS pension at retirement. How you allocate those accounts should reflect what the pension already does for you — not ignore it.
To understand the structural income gap your savings need to fill, see The Biggest Income Gap Risks Teachers Face in Retirement.
The Risks That Actually Matter in Retirement
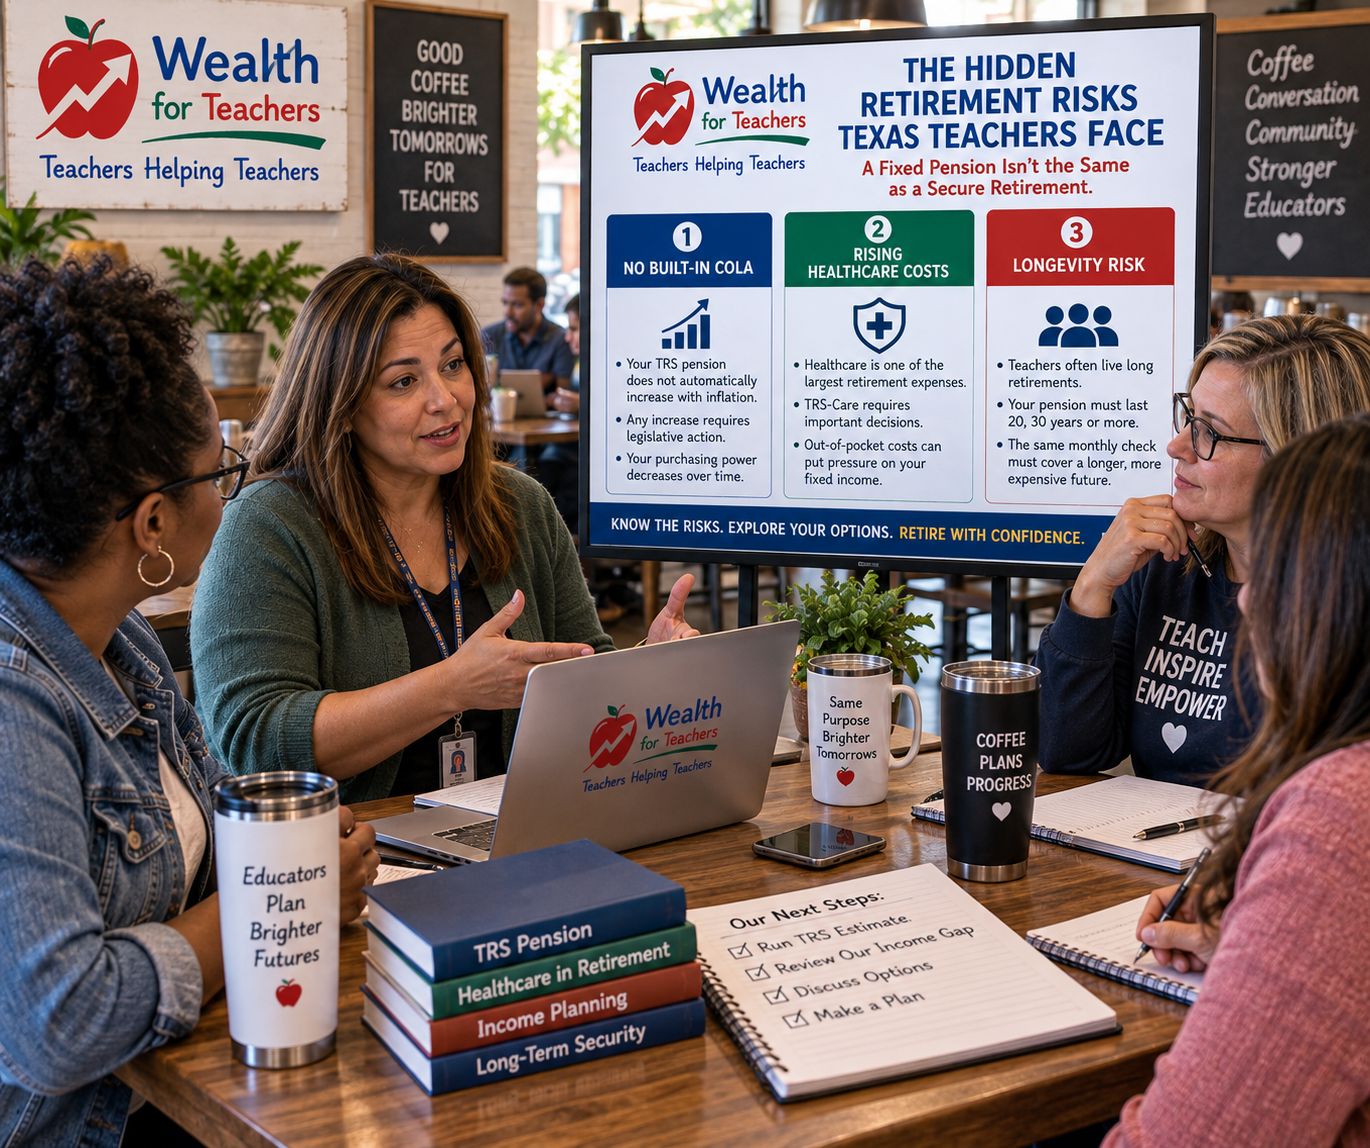
Most pre-retirement investment conversations focus on market risk. In retirement, three other risks often matter more for Texas teachers:
1. Inflation Risk
Because TRS pension payments are not automatically indexed to inflation, the purchasing power of your monthly annuity erodes over time. A pension that covers your expenses today may cover significantly less in 15 or 20 years. Your portfolio needs to grow enough — or generate enough income — to compensate for that erosion.
This is one reason a fully “conservative” portfolio of cash and short-term bonds may actually be riskier for a Texas teacher than it appears. See How Inflation Really Impacts TRS Pension Over Time for a detailed breakdown of this specific risk.
2. Longevity Risk
Teachers who retire at 60 or 62 may spend 25 to 30 years in retirement. A portfolio allocated too conservatively at retirement may not sustain that duration. The risk of outliving your savings is real, and it is compounded by a fixed pension that loses purchasing power over time.
3. Sequence-of-Returns Risk
As noted above, the order in which returns occur matters enormously once you are withdrawing. A portfolio structured without a short-term income buffer forces you to sell long-term assets at the worst possible time — during market downturns.
Aligning Your Portfolio to Your Income Needs
The most practical framework for retired teachers is to align the portfolio to income needs in distinct time segments — commonly called a “bucket” approach.
Near-Term Bucket (Years 1–3)
Hold 1 to 3 years of spending in excess of your pension income in cash, money market accounts, or short-term fixed income. This buffer means you do not need to sell equities during a market downturn. It buys time.
Mid-Term Bucket (Years 4–10)
Allocate this segment to moderate-risk income-producing assets — bond funds, dividend-paying equities, or similar holdings. The goal is to replenish the near-term bucket as it depletes, while generating some growth.
Long-Term Bucket (Years 10+)
This portion can carry more equity exposure. Given that a Texas teacher retiring at 62 may live into their late 80s, this bucket has decades to grow. Completely abandoning equities in retirement is a common mistake that accelerates purchasing power loss.
The specific percentages in each bucket depend on your pension income, your spending needs, your Social Security eligibility, and how long you expect your savings to need to last. There is no universal ratio that works for every teacher.
For guidance on how much you can draw from these buckets without depleting your savings, see Understanding Safe Withdrawal Rates for Teachers.
For a deeper look at building guaranteed income coverage, see How to Build a Retirement Income Floor as a Teacher.
How to Make the Right Decision for Your Situation
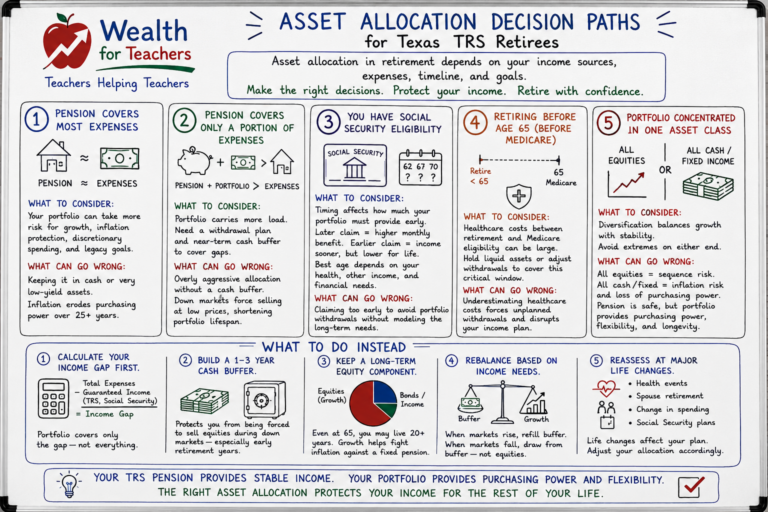
Asset allocation in retirement is not one-size-fits-all. The right structure depends on the combination of income sources, liabilities, and timeline specific to each teacher. Here are five decision paths that commonly apply to Texas TRS retirees.
Path 1: Your Pension Covers Most Essential Expenses
When it applies: A teacher with 28 or more years of service whose pension comes close to covering housing, utilities, food, and healthcare costs.
What to consider: Your portfolio can carry more risk because it is not being pressed into basic income support. It can focus on inflation protection, discretionary spending, and legacy goals.
What can go wrong: Treating the portfolio as fully optional and keeping it in cash or very low-yield instruments. Over a 25-year retirement, inflation erodes purchasing power significantly, and the portfolio could have been doing meaningful work.
Path 2: Your Pension Covers Only a Portion of Expenses
When it applies: A teacher who retired earlier with fewer years of service, or whose expenses have grown faster than their pension income.
What to consider: Your portfolio carries a heavier load. You need a more deliberate income-generation strategy — including a clear withdrawal plan and near-term buffer — because pulling from the portfolio in a down market is unavoidable if you haven’t planned ahead.
What can go wrong: Keeping an overly aggressive equity allocation without a cash buffer. The first major market correction forces large liquidations at low prices, potentially shortening the portfolio’s lifespan by years.
Path 3: You Have Social Security Eligibility
When it applies: Approximately 96% of Texas public-school employees do not pay into the Social Security system, which makes personal savings more critical. However, if you have contributed to Social Security through prior employment or a spouse’s record, you may be eligible to receive benefits.
What to consider: If you are eligible, the timing of when you claim Social Security meaningfully affects how much your portfolio needs to generate in the early years of retirement. Claiming later increases your monthly benefit through delayed retirement credits, but requires the portfolio to fill a larger gap in the interim years. Claiming earlier provides income sooner but at a permanently reduced monthly amount. The right claiming age depends on your individual circumstances — including health, longevity expectations, other income sources, and financial need — and these decisions are generally not reversible, so review your options carefully.
What can go wrong: Claiming Social Security early to avoid drawing from the portfolio without modeling whether the reduced lifetime benefit is actually worth it given your specific situation. In some scenarios, delayed claiming and higher portfolio withdrawals early produces better long-term outcomes — but this depends on factors including your health, life expectancy, and portfolio sustainability.
Path 4: You Are Retiring Before Age 65
When it applies: A Texas teacher who meets TRS eligibility criteria and retires before Medicare eligibility at age 65.
What to consider: Healthcare costs between retirement and Medicare eligibility represent a real, potentially large expense. These costs need to be accounted for in your portfolio structure — either by holding additional liquid assets during that window or by adjusting withdrawal rates to absorb them.
What can go wrong: Underestimating healthcare costs during the pre-Medicare window can force unplanned portfolio withdrawals, which disrupts the income alignment you built.
Path 5: Your Portfolio Is Heavily Concentrated in One Asset Class
When it applies: A teacher who rolled over a 403(b) at retirement and left it entirely in either equities or a fixed-rate account.
What to consider: Concentration in either direction carries risk. All equities exposes you to sequence risk. All fixed-rate or cash exposes you to inflation risk and the erosion of purchasing power.
What can go wrong: Assuming that because your pension is “safe,” the portfolio does not require active thought. The pension handles income stability. The portfolio handles purchasing power, flexibility, and longevity — all of which can be undermined by concentrated allocation.
What to Do Instead
Rather than using the same allocation you had during your working years or flipping entirely to conservative holdings at retirement, a better approach works like this:
- Calculate your income gap first. Subtract your guaranteed income (TRS pension, any Social Security) from your projected total monthly expenses. The portfolio needs to cover only that gap — not your entire retirement.
- Build a 1-to-3-year cash or near-cash buffer. This protects you from being forced to sell equities during downturns in the early years when sequence-of-returns risk is highest.
- Keep a long-term equity component. Even at 65, most Texas teachers will live for 20 or more additional years. Completely removing growth assets accelerates purchasing power loss from inflation, which compounds against a fixed pension.
- Rebalance based on income needs, not just market movements. When markets rise, refill your near-term buffer. When markets fall, draw from that buffer rather than equities.
- Reassess allocation at major life changes. Healthcare events, a spouse’s retirement, a change in spending, or a shift in Social Security plans all affect how the portfolio should be structured.
Quick Self-Check Before You Move Forward
Before making changes to your portfolio — or before assuming your current allocation is working — run through these five diagnostic questions:
- Do you know exactly how much your TRS pension will pay each month after any applicable survivor benefit elections? If you haven’t calculated this using the exact formula, your income plan may be built on an estimate that doesn’t hold up.
- Have you identified the exact monthly gap between your guaranteed income and your projected spending? If not, you don’t yet know how much pressure your portfolio is actually under.
- Do you have at least one year of spending needs (above pension income) in liquid, low-risk holdings? If not, a market downturn could force you to sell long-term assets at precisely the wrong time.
- Have you stress-tested your withdrawal rate against a 20-to-30-year retirement horizon? A withdrawal rate that works for 15 years may deplete your portfolio well before your life expectancy, especially given a fixed pension eroded by inflation.
- Does your current asset allocation reflect what your portfolio actually needs to do in retirement — or does it still reflect what it was doing while you were accumulating? Many retired teachers are still holding the same mix they had at 55. That may no longer be appropriate.
Common Questions Texas Teachers Ask
Does my TRS pension count as part of my asset allocation?
Not in the traditional sense. Your TRS pension is a defined benefit — a guaranteed monthly payment for life, not an investable asset you can rebalance. However, it does function as the equivalent of a very large fixed-income position when thinking about total income risk. A teacher with a robust pension effectively already holds significant “conservative income” and may be able to carry more equity risk in their supplemental portfolio than they realize.
Should I move my 403(b) to something more conservative right when I retire?
Not automatically. The right allocation depends on how much your pension covers, how long your savings need to last, and whether you have a near-term income buffer. Moving entirely to conservative assets at retirement is a common reflex — but it can accelerate purchasing power loss, especially given that TRS pensions are not inflation-adjusted.
What if I have both a 403(b) and a 457 plan?
These accounts can serve different roles in your retirement income structure. A governmental 457(b) plan does not impose the 10% early-withdrawal penalty that applies to a 403(b) before age 59½, which can provide flexibility in the years before that threshold for teachers who retire early. Coordinate these accounts intentionally based on your income timeline rather than treating them as identical.
How does Social Security affect my portfolio allocation?
If you are eligible for Social Security benefits, when you claim matters. Claiming early means your portfolio carries more of the income load in later years due to the permanently reduced monthly benefit. Delaying means a larger guaranteed income stream eventually reduces the portfolio’s burden, but requires larger portfolio withdrawals in the interim. The appropriate claiming age depends on your individual circumstances, including health, longevity expectations, and overall financial picture.
Is a 60/40 portfolio still appropriate for a retired Texas teacher?
It depends entirely on your income gap, your pension size, and your timeline. A teacher whose pension covers 90% of expenses may be able to tolerate more equity exposure than that ratio suggests. A teacher whose pension covers only 50% of expenses and who is drawing heavily from savings may need a more conservative near-term structure even if the long-term bucket holds equities.
Why Most Teachers Don’t Discover Gaps Until It’s Too Late
The most dangerous retirement planning errors for Texas teachers are not the obvious ones. They are the assumptions that seem reasonable until they are tested by a market decline, an unexpected health event, or simply the slow erosion of purchasing power over 20 years.
A fixed TRS pension that seems adequate at 62 may feel meaningfully tighter at 72 — and genuinely strained at 80. The TRS pension is not automatically adjusted for inflation, which means that although it may be enough to cover expenses when you first retire, over time your monthly annuity’s purchasing power will decrease. That erosion is quiet, gradual, and often invisible until it becomes a real problem.
Similarly, a portfolio left in its accumulation-phase allocation for the first five years of retirement can sustain serious, permanent damage from an early market downturn. Many teachers discover this after the fact — when recovery is no longer fully possible at the portfolio level.
The only way to avoid these outcomes is to test your assumptions before you lock in major decisions — not after.
Get Your TRS Analysis
Your TRS pension is a significant asset — but it doesn’t work in isolation. The way you structure the savings around it determines whether you maintain your standard of living throughout a 20-to-30-year retirement or begin facing income shortfalls a decade in.
If you haven’t modeled how your current allocation aligns with your pension income, your expense gap, and your long-term timeline, there are likely decisions that deserve a closer look.
Get Your TRS Analysis and see how your full retirement income picture fits together — before you commit to a structure that may not hold up under real-world conditions.