Why Texas Teachers Without a Retirement Income Floor Risk Running Out of Money
Most Texas teachers spend decades building a career inside the classroom and far less time building a plan for what happens after it ends. The result is a retirement that looks fine on paper but collapses under the weight of real expenses, unexpected health costs, and inflation that the numbers never accounted for.
Texas teachers can also run a full pension estimate using the Texas Teacher Retirement Calculator to better understand their retirement outlook.
The concept of an income floor retirement teachers need is straightforward: identify the guaranteed, recurring income sources that will cover your essential expenses every month for the rest of your life — regardless of what markets do, how long you live, or what surprises arise. Everything built on top of that floor is discretionary. Everything built below it is risk.
For Texas teachers covered by the Teacher Retirement System of Texas (TRS), the pension is the natural foundation of that floor. But a pension alone rarely covers everything. Understanding how to layer additional guaranteed income on top of it — and how to avoid the decisions that permanently shrink that floor — is one of the most consequential financial moves a Texas teacher can make.
For a full overview of how TRS decisions connect to your long-term financial picture, start with the Texas Teacher Retirement Planning Guide.
Most retirement plans fail not because the numbers were wrong at the start, but because they were never stress-tested against real-world conditions: a spouse who outlives the pension, healthcare costs that arrive early, or a fixed benefit that loses ground to inflation year after year. A properly structured income floor is what prevents those scenarios from becoming crises.
What Is a Retirement Income Floor for Teachers?
An income floor is the guaranteed monthly income you can count on to cover your non-negotiable expenses in retirement: housing, utilities, food, transportation, insurance premiums, and healthcare basics. If those needs are covered by guaranteed income sources, you have a floor. If they depend on portfolio withdrawals or assumptions about investment returns, you have a risk.
Run Your Free Texas Teacher Retirement Analysis
Use the TRS calculator to estimate your pension and identify potential income gaps.
Teachers often confuse total retirement assets with retirement income security. They are not the same thing. A $400,000 savings account sounds substantial until you realize it must last 25 or 30 years while also covering healthcare gaps, supporting a spouse, and competing with rising prices.
An income floor approach separates your financial life into two zones:
- The floor: Guaranteed income that covers essential expenses every month
- The upside: Savings, investments, and flexible assets that fund wants, emergencies, and legacy goals
The floor must be built intentionally. It does not assemble itself.
Your TRS Pension: The First Layer of the Floor
The TRS pension plan is a defined benefit plan, meaning retirement benefits are determined using a formula established by Texas law — not by your contribution account balance. That distinction matters enormously for income floor planning. Your benefit does not depend on market conditions or how you managed your investments.
The pension formula is calculated using 2.3% (the multiplier) times the average of the five highest annual creditable salaries, times years of credited service, to arrive at the annual standard annuity — except for members who are grandfathered, in which case the three highest annual salaries are used.
In plain terms: Annual Pension = (Years of Service × 0.023) × Final Average Salary
Here is a concrete example. A teacher retires with 28 years of service and a final average salary of $62,000:
- 28 × 0.023 = 0.644
- 0.644 × $62,000 = $39,928 per year, or roughly $3,327 per month
That $3,327 per month is guaranteed for life. It does not fluctuate. It does not disappear if the market drops. For most Texas teachers, this is the single most powerful income floor asset they will ever have — and the decisions made around it (timing, payment option, survivor benefit election) directly affect how strong that floor actually is.
Retiring earlier than your eligibility threshold can trigger early-age reduction factors that permanently lower your monthly benefit. Unreduced service retirement — sometimes called normal age retirement — means your TRS benefit is calculated using the standard annuity formula and is not reduced because of early age. Retiring before reaching that threshold means accepting a smaller floor for the rest of your life.
The payment option you elect at retirement also shapes survivorship. Choosing a higher monthly benefit for yourself may reduce or eliminate what your spouse receives after your death. That decision cannot be reversed after your retirement is finalized.
Social Security as a Second Layer
Many Texas teachers worked in Social Security-covered employment before or alongside their teaching career — as part-time employees, in summer jobs, or in another career entirely. If you have enough Social Security work credits from covered employment, you may be eligible for a Social Security retirement benefit.
A significant law change affects how Social Security interacts with TRS pensions. The Social Security Fairness Act, HR 82, was signed into law on January 5, 2025. The Act eliminates the reduction of Social Security benefits while entitled to public pensions from work not covered by Social Security. This means the Windfall Elimination Provision (WEP) and Government Pension Offset (GPO) — which previously reduced or eliminated Social Security benefits for many public school teachers — no longer apply to benefits payable beginning January 2024.
Only people who receive a pension based on work not covered by Social Security may see benefit increases under the new law. According to TRS, approximately 96% of Texas public school employees do not pay into Social Security, which means the repeal of WEP and GPO is particularly significant for this population.
If you are among the teachers who do qualify for Social Security, the timing of when you claim that benefit is a meaningful income floor decision. Claiming early locks in a permanently reduced monthly payment. Delaying past your full retirement age increases your monthly benefit through delayed retirement credits, though the right claiming age depends on your individual health, income needs, other guaranteed income sources, and personal circumstances. For guidance on how that timing decision plays out specifically for teachers, see Should Teachers Delay Social Security Benefits?
Additional Guaranteed Income Layers
For many Texas teachers, the TRS pension and — where applicable — Social Security still leave a monthly gap between guaranteed income and actual expenses. Filling that gap with reliable, predictable income sources is what completes the floor.
Options teachers use to build additional income layers include:
- Fixed annuities: A lump-sum payment to an insurance company converts to a guaranteed monthly income stream for life or a defined period. This can fill a specific dollar gap in the floor with certainty.
- Deferred compensation savings (403(b) or 457 plans): These are not guaranteed income sources by themselves, but systematic withdrawals can be structured to supplement guaranteed income in a reliable, repeatable way.
- Rental income: For teachers who own property, a consistently occupied rental can function like a second pension — but unlike a pension, it carries management risk, vacancy risk, and maintenance cost variability.
- Spousal income or pensions: If a spouse has their own pension or Social Security, that income contributes directly to the household floor and affects how aggressively the TRS payment option needs to protect survivor income.
To understand how long your savings need to stretch alongside these income sources, read How Long Will Your Retirement Savings Last as a Teacher?
What Can Silently Weaken Your Income Floor
A strong income floor today can erode over time. Texas teachers face specific pressures that chip away at guaranteed income purchasing power:
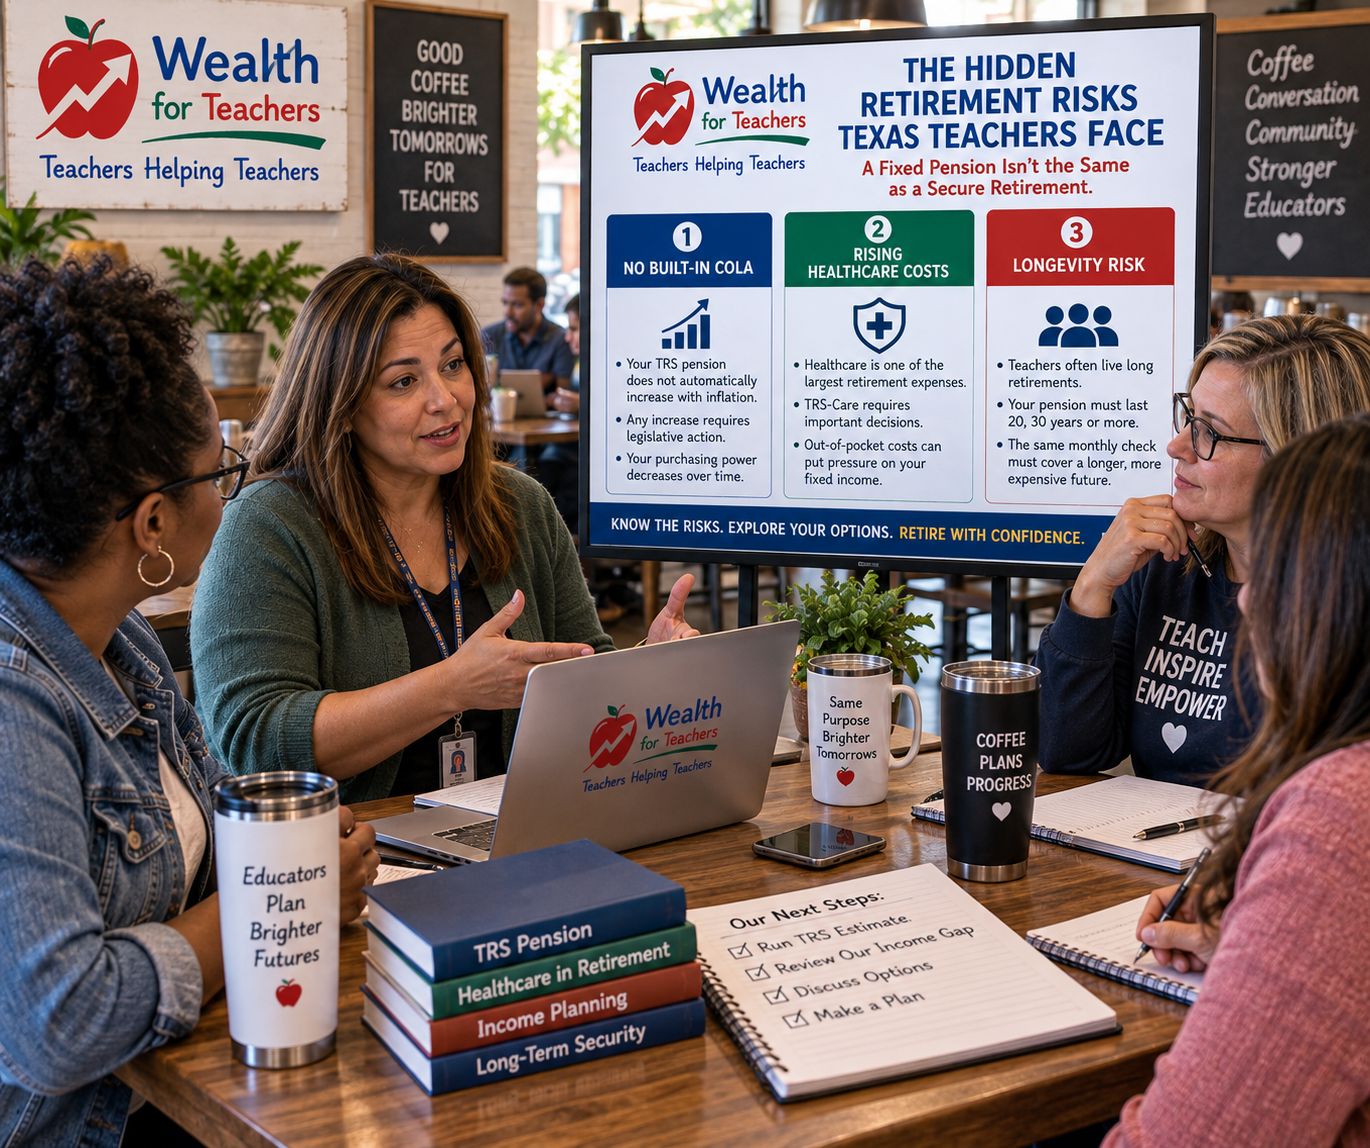
- Inflation: TRS pension payments are fixed unless the Texas Legislature approves a cost-of-living adjustment, which is not guaranteed and has not been consistent. A $3,300 monthly benefit today will buy meaningfully less in fifteen years if inflation runs at historical averages. For a deeper look at this risk, see How Inflation Really Impacts TRS Pension Over Time.
- Healthcare costs: TRS-Care is available to eligible retirees, but premiums, coverage tiers, and out-of-pocket costs can shift. Healthcare spending tends to increase with age, which means the gap between your fixed income floor and your actual healthcare expenses can widen over time.
- Early retirement: Retiring several years before your unreduced benefit eligibility date can reduce your monthly pension permanently — shrinking the floor from the very first payment.
- Lump-sum pension elections: Some teachers have access to partial lump-sum options at retirement. Taking a lump sum reduces your monthly annuity for life. If that monthly reduction drops your floor below your essential expenses, you have traded security for a one-time payment.
- Survivor benefit elections: Choosing a payment option that maximizes your monthly income but leaves your spouse with little or no survivor benefit means the household income floor collapses if you die first.
Understanding where income gaps can form — and how to close them — is covered in detail in The Biggest Income Gap Risks Teachers Face in Retirement.
What to Do Instead
Rather than assembling a retirement plan based on rough estimates and good intentions, Texas teachers can take specific steps to build and protect a genuine income floor:
- Calculate your TRS benefit at multiple retirement dates. Log in to the MyTRS member portal and select the Benefit Calculator located under the Planning Tools tab. The calculator will automatically import current data from your TRS records, including your tier, years of service credit, and highest annual salaries. Run the numbers at your earliest eligibility date and two to three years later. The difference in monthly income is often large enough to change your decision.
- Identify your floor gap. Add up your essential monthly expenses — housing, utilities, food, transportation, insurance, healthcare. Then add up your guaranteed monthly income sources. The difference is your gap. If it is positive, your floor is complete. If it is negative, that gap needs a plan.
- Think about survivor income before you elect a payment option. Model what your spouse’s monthly income would be under each payment option if you died in year one, year ten, and year twenty of retirement. The option that looks best for you may leave your spouse in a very difficult financial position.
- Do not assume Social Security will handle the gap. Approximately 96% of Texas public school employees do not pay into Social Security. Even those who do qualify may receive less than expected based on their work history. Confirm your actual Social Security earnings record before building it into your floor projection.
- Address inflation now, not later. If your TRS pension is your primary income source and it does not increase automatically with inflation, consider building a supplemental income strategy — through savings, investments, or other income sources — that can absorb rising costs over a multi-decade retirement.
- Consider withdrawal rate strategy for savings. The portion of your retirement funded by savings rather than guaranteed income requires a plan for how much to withdraw each year without depleting it too early. See Understanding Safe Withdrawal Rates for Teachers for a teacher-specific look at this decision.
How to Make the Right Decision for Your Situation
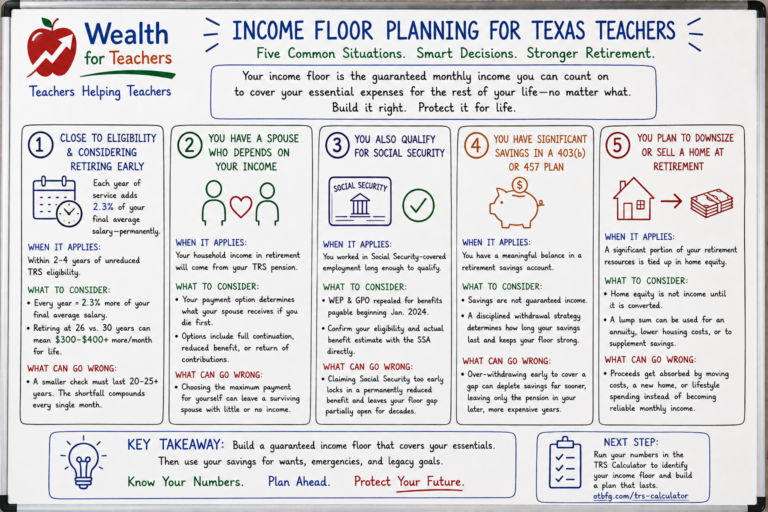
No two Texas teachers retire in identical circumstances. Here are five common situations and what each one means for income floor planning:
1. You Are Close to Eligibility and Considering Retiring Early
When it applies: You are within two to four years of unreduced TRS eligibility and feeling the pull of an early exit.
What to consider: Each year of additional service adds 2.3% of your final average salary to your annual pension — permanently. The gap between retiring at 26 years versus 30 years of service can easily exceed $300 to $400 per month for the rest of your life.
What can go wrong: Teachers who retire early to access the pension sooner often underestimate how many decades that smaller check must last — and how much that monthly shortfall compounds over twenty or twenty-five years.
2. You Have a Spouse Who Depends on Your Income
When it applies: Your household income in retirement will primarily or entirely come from your TRS pension.
What to consider: The payment option you elect at retirement determines what your spouse receives if you die first. Some options provide full continuation; others provide a reduced benefit or nothing beyond a return of contributions.
What can go wrong: Choosing the maximum monthly payment for yourself without modeling survivorship scenarios can leave a surviving spouse with drastically reduced income at the worst possible time.
3. You Also Qualify for Social Security
When it applies: You worked in Social Security-covered employment long enough to qualify for a benefit based on your own earnings record.
What to consider: The repeal of WEP and GPO, effective for benefits payable beginning January 2024, means your Social Security benefit is no longer reduced because of your TRS pension — if you receive a pension from non-Social Security-covered work. Confirm your eligibility and actual benefit estimate through the Social Security Administration directly.
What can go wrong: Claiming Social Security too early locks in a permanently reduced benefit. If you are using Social Security to fill a floor gap, claiming at the wrong time can leave that gap partially open for decades.
4. You Have Significant Savings in a 403(b) or 457 Plan
When it applies: You contributed throughout your career to a deferred compensation account and have a meaningful balance at retirement.
What to consider: Savings accounts are not guaranteed income sources. They require a disciplined withdrawal strategy to produce reliable income without depleting too quickly. How you convert those savings to income — and at what rate — determines whether your floor holds.
What can go wrong: Over-withdrawing in early retirement, especially to compensate for an income gap, can deplete savings far earlier than projected — leaving you with only the pension in your later, often more expensive years.
5. You Plan to Downsize or Sell a Home at Retirement
When it applies: A significant portion of your expected retirement resources is tied up in home equity.
What to consider: Home equity is not income until it is converted. A lump sum from a home sale can be used to fund an annuity, reduce housing costs, or supplement savings — but it requires a conversion plan to function as an income floor layer.
What can go wrong: Counting on home equity without a clear conversion strategy often results in proceeds that are absorbed quickly by moving costs, a new housing purchase, or lifestyle spending — rather than being directed into reliable monthly income.
Common Questions Texas Teachers Ask
Will my TRS pension be enough to cover all my expenses?
For some teachers — particularly those with 30 or more years of service and relatively modest fixed expenses — the pension alone may cover essential costs. For most, it covers a significant portion but leaves a monthly gap that requires additional income sources or thoughtful withdrawal planning.
Does my TRS pension increase with inflation?
The standard TRS annuity is a fixed monthly amount. Cost-of-living increases require Texas Legislature approval and are not automatically guaranteed. This is one of the most underestimated risks in Texas teacher retirement planning.
Can I lose my TRS pension?
The TRS pension plan is a defined benefit plan, meaning retirement benefits are determined using a formula established by Texas law. Once you retire and begin receiving benefits, your monthly payment is protected under that structure. However, decisions made at retirement — such as lump-sum elections or payment option choices — permanently affect the monthly amount you receive.
How does the Social Security Fairness Act affect Texas teachers?
The law repeals the Windfall Elimination Provision and Government Pension Offset, both of which could reduce Social Security benefits when someone received a pension based on work not covered by Social Security. The law applies with respect to benefits payable for months after December 2023. Texas teachers who qualify for Social Security benefits based on covered employment outside of TRS-covered positions should verify their updated benefit estimate directly with the SSA.
What happens to my income floor if I retire before 65 and need health coverage?
Medicare eligibility generally begins at age 65. If you have qualifying current-employment group health coverage, you may be able to delay Medicare enrollment without penalty and enroll later during a Special Enrollment Period. Retiring before 65 without other qualifying coverage means you need to bridge a healthcare coverage gap — through TRS-Care, a spouse’s employer plan, marketplace coverage, or another source. That bridging cost is a real expense that belongs in your income floor calculation, not an afterthought.
Should I take the lump-sum option if TRS offers it?
Partial lump-sum options at retirement permanently reduce your monthly annuity. Whether that trade-off makes sense depends on your other income sources, your health, your survivorship needs, and what you plan to do with the lump sum. A higher lump sum in exchange for a lower monthly floor is a significant and irreversible trade-off that deserves careful analysis before you elect it.
Quick Self-Check Before You Move Forward
Use these questions to identify gaps or uncertainty in your current retirement income plan:
- Do you know your exact TRS monthly benefit at your planned retirement date? Not an estimate from memory — the actual figure from the MyTRS Benefit Calculator based on your current service credit and projected final average salary?
- Have you identified every essential monthly expense you will need to cover in retirement, including healthcare premiums, any mortgage or rent, and any recurring costs that will not disappear after you stop working?
- Does your guaranteed monthly income — pension, Social Security (if eligible), or other fixed sources — fully cover those essential expenses? If not, how large is the gap, and what specific source will close it?
- Have you modeled what your spouse’s monthly income would be if you died in the first year of retirement? Is that number sufficient for them to cover their own essential expenses?
- Do you know whether your TRS pension would be reduced for early age retirement under your tier, and have you calculated the lifetime cost of that reduction if you retire before reaching unreduced eligibility?
If any of these questions produced uncertainty, that uncertainty represents a real financial risk — not a planning detail to address later.
Most Teachers Discover Gaps Too Late
The most common pattern in Texas teacher retirement planning is this: a teacher works for decades, accumulates a solid service record, and assumes the TRS pension will handle most of the heavy lifting. They retire, elect a payment option without fully modeling survivorship, and begin drawing benefits. Within a few years, inflation has reduced real purchasing power, healthcare costs have grown, and the income floor that looked adequate in year one is visibly cracking by year five or ten.
The gaps are rarely catastrophic in isolation. A $200-per-month shortfall today becomes a $400-per-month shortfall in fifteen years when you factor in rising costs. A survivor benefit decision that seemed minor becomes a crisis when the higher-earning spouse dies first. These are not edge cases — they are the pattern for teachers who never stress-tested their assumptions while they still had time to adjust.
Testing your income floor plan before you retire — not after — is the difference between discovering a gap you can fix and discovering one you cannot.
Get Your TRS Analysis
Understanding your TRS pension is only the first step. Knowing how it fits into a complete, stress-tested income floor is what protects you for the long term. A personalized TRS analysis can identify your floor gap, model your payment options, and show exactly where your retirement plan is strong and where it needs reinforcement.