Why Texas Teachers Run Out of Money in Retirement — and How to Prevent It
Running out of money is more common than teachers think. A Texas Teacher Retirement System (TRS) pension provides a guaranteed monthly income for life, but for many teachers that pension alone does not cover every cost retirement brings. The gap between what the pension pays and what retirement actually costs is where financial problems quietly begin.
Texas teachers can also run a full pension estimate using the Texas Teacher Retirement Calculator to better understand their retirement outlook.
Understanding why teachers run out of money in retirement is not about predicting the worst. It is about identifying the specific decisions, assumptions, and oversights that slowly drain a retirement income — and correcting them before they cause lasting harm.
This article breaks down the real causes of retirement shortfalls for Texas teachers, walks through the decisions that matter most, and explains what to do differently before and after you leave the classroom.
For broader context on how TRS fits into a complete retirement strategy, start with this Texas Teacher Retirement Planning Guide.
Why Most Retirement Plans Fail Before They Are Tested
Most retirement plans look fine on paper. The problem is that paper plans are never exposed to real-world variables: a prolonged illness, a market downturn in the first few years of retirement, a spouse who outlives income projections by two decades, or healthcare costs that double within ten years. A plan that has never been stress-tested against these possibilities is not really a plan — it is an estimate dressed up as one.
Run Your Free Texas Teacher Retirement Analysis
Use the TRS calculator to estimate your pension and identify potential income gaps.
Texas teachers face a specific version of this problem. The TRS pension is a reliable foundation, but it is built on assumptions about your final salary, years of service, and how long those dollars will need to last. When those assumptions are never questioned, the gaps go unnoticed until retirement has already begun.
The Pension Gap: What TRS Covers and What It Doesn’t
The basic formula used to calculate a TRS standard annuity involves three factors: years of service, final average salary, and a flat multiplier of 2.3%. That formula is straightforward, but what it produces may not be enough.
Consider a teacher who retires with 28 years of service and a final average salary of $58,000. The calculation looks like this:
- 28 × 0.023 = 0.644 (64.4%)
- 64.4% × $58,000 = $37,352 per year, or roughly $3,113 per month
That is a meaningful income — but it is not a complete one. Property taxes, healthcare premiums, travel, home maintenance, and rising grocery costs are not adjusted for when TRS calculates your benefit. If your monthly expenses in retirement are $4,500, a $3,113 pension leaves a gap of nearly $1,400 every single month. Over a 20-year retirement, that gap adds up to more than $330,000.
Teachers who do not plan for that gap are the ones who eventually run out of money.
Poor Planning: The Silent Starting Point
Poor planning rarely looks like poor planning in the moment. It looks like putting off the question until “closer to retirement.” It looks like assuming the pension will be enough without running the numbers. It looks like not knowing which TRS membership tier you belong to, or how an early retirement election affects your monthly benefit for the rest of your life.
Changes to the TRS retirement plan over the years have resulted in several distinct membership categories, each with its own retirement eligibility requirements and early-age reductions. TRS identifies these as membership tiers, and your tier is determined by the date you entered TRS membership, your grandfathered status, and the amount of service credit you had on August 31, 2014.
Retiring under the wrong assumptions about your tier — or triggering an early-age reduction that permanently reduces your monthly benefit — is one of the most common and costly planning mistakes Texas teachers make.
Other common planning failures include:
- Not accounting for healthcare costs between retirement and Medicare eligibility at age 65
- Failing to build supplemental savings through a 403(b) or other account during working years
- Not considering which TRS annuity payment option is best for a surviving spouse
- Underestimating how quickly living costs rise in the first ten years of retirement
Understanding how to build a retirement income floor as a teacher is one of the clearest ways to translate TRS math into a livable income plan before retirement begins.
Early and Unplanned Withdrawals
For teachers who carry supplemental retirement savings — such as a 403(b) or an IRA — the order and timing of withdrawals matter significantly. Drawing from investment accounts too early, too aggressively, or during a market downturn can permanently reduce a portfolio’s ability to recover and last.
This risk is amplified in the early years of retirement, when a large withdrawal during a down market locks in losses that would otherwise have recovered. A portfolio that loses value and is simultaneously being drawn down may never fully recover — even if the market does.
Teachers who retire before age 59½ face an additional consideration: early withdrawals from certain retirement accounts may be subject to taxes and potential penalties depending on the account type and applicable IRS rules. The specific rules depend on the account structure, so this is an area where the details matter and assumptions should be verified.
Understanding whether and how to shift investments before retirement can help teachers avoid drawing from the wrong accounts at the wrong time.
How Inflation Erodes a Fixed Pension Income
The TRS pension is a fixed monthly payment. It does not automatically adjust upward each year to match rising prices. That means every year that inflation runs above zero, the real purchasing power of a TRS benefit quietly shrinks.
Over a 20- or 25-year retirement, even modest average inflation produces a meaningful reduction in what that monthly check can actually buy. A teacher who retired in her early 60s with a pension that covered her expenses comfortably may find by her late 70s that the same dollar amount now falls noticeably short — because groceries, utilities, and healthcare all cost more.
This is not a hypothetical risk. It is a predictable, mathematical outcome of receiving a fixed income in an environment where costs continue to rise. Understanding what happens if inflation stays high in retirement is critical context for any Texas teacher building a long-term income plan.
Inflation risk is one of the most underestimated reasons why teachers run out of money. The pension feels adequate at retirement. The problem emerges gradually — and by the time it is obvious, flexibility has often been lost.
Longevity: The Risk No One Plans For
Longevity is the multiplier behind every other retirement risk. The longer a teacher lives, the longer inflation erodes purchasing power, the longer healthcare costs accumulate, and the longer any supplemental savings must last.
Teachers who retire in their late 50s or early 60s may realistically face a 30-year retirement. A financial plan built around a 15- or 20-year window will eventually fail. The pension pays for life — but supplemental savings, healthcare coverage, and spending plans may not be structured to go the distance.
Longevity also affects decisions around TRS annuity payment options. Choosing a payment option that maximizes your monthly benefit may leave a surviving spouse with reduced or no continuing income. That is a decision with consequences that extend decades beyond the day it is made.
Social Security and What Changed for Texas Teachers
Texas public school employees generally do not pay into Social Security through their school district employment — according to TRS, approximately 96% of Texas public school employees do not pay into Social Security — which means many Texas teachers have limited or no Social Security benefit based on their teaching career alone. However, teachers who worked in Social Security-covered jobs before or outside of teaching may be eligible for Social Security benefits based on that work history.
For years, two federal rules — the Windfall Elimination Provision (WEP) and the Government Pension Offset (GPO) — reduced or eliminated Social Security benefits for many public employees, including teachers, who also received a government pension. The Social Security Fairness Act of 2023 was signed into law on January 5, 2025, and repealed both the WEP and GPO. The repeal applies to benefits payable for months after December 2023, meaning December 2023 was the last month those provisions applied.
Beginning February 25, 2025, SSA began adjusting monthly benefit payments to people whose benefits had been affected by the WEP and GPO. Eligible beneficiaries received a one-time payment covering the increase in their benefit amount back to January 2024, the first month when WEP and GPO no longer applied.
For Texas teachers who qualify for Social Security benefits — whether through a spouse’s record or through their own covered work history — this change may meaningfully increase their retirement income. Teachers who have not yet filed for Social Security and who may now qualify for a larger benefit should review their situation with the Social Security Administration directly.
What to Do Instead
Avoiding a retirement shortfall requires specific, proactive steps — not general intentions. For Texas teachers, that means:
- Know your TRS tier and your exact retirement eligibility date. Confirm whether your benefit would be reduced for early age, and by how much.
- Run the pension math before you make any retirement decision. Use your actual final average salary estimate and your realistic retirement date to calculate your monthly benefit — not a round number assumption.
- Identify the gap between your projected pension and your projected monthly expenses. Be realistic. Include healthcare, travel, home maintenance, and taxes.
- Build supplemental savings systematically during your working years. A 403(b) or similar account provides flexibility that the pension cannot.
- Plan for healthcare costs explicitly. If you retire before age 65, you need a coverage bridge to Medicare. That cost should be part of your income plan.
- Stress-test your income plan against inflation and longevity. A plan that works at 62 should also hold up at 82.
The right asset allocation in retirement is one of the key levers that determines how long supplemental savings last — and how well a teacher’s income plan holds up against real-world conditions.
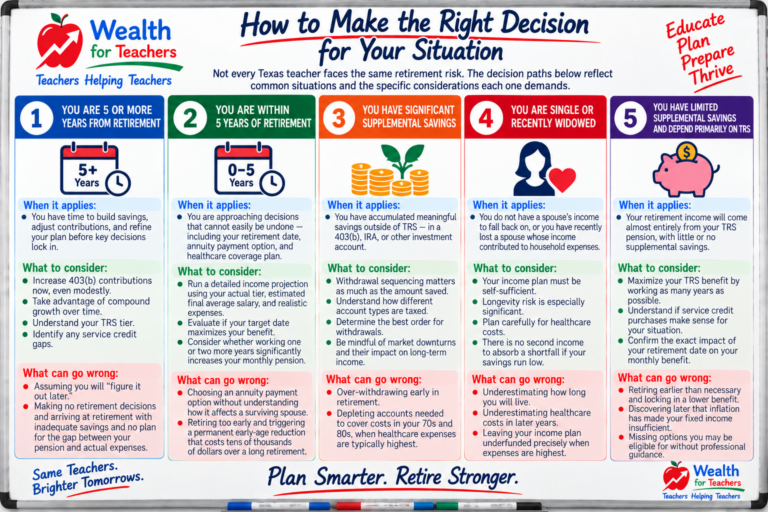
How to Make the Right Decision for Your Situation
Not every Texas teacher faces the same retirement risk. The decision paths below reflect common situations and the specific considerations each one demands.
Path 1: You Are 5 or More Years From Retirement
When it applies: You have time to build savings, adjust contributions, and refine your plan before key decisions lock in.
What to consider: This is the window where supplemental savings have the most impact. Increasing 403(b) contributions now, even modestly, compounds significantly over time. You also have time to understand your TRS tier and identify any service credit gaps.
What can go wrong: Assuming you will “figure it out later” is the most common mistake in this window. Teachers in this group often make no retirement decisions at all — and arrive at retirement with inadequate savings and no plan for the gap between the pension and their actual expenses.
Path 2: You Are Within 5 Years of Retirement
When it applies: You are approaching the decisions that cannot easily be undone — including your retirement date, annuity payment option, and healthcare coverage plan.
What to consider: Run a detailed income projection using your actual tier, estimated final average salary, and realistic expenses. Evaluate whether retiring at your targeted date maximizes your benefit or whether waiting one or two additional years meaningfully increases your monthly pension.
What can go wrong: Choosing an annuity payment option without understanding how it affects a surviving spouse. Retiring one or two years too early and triggering a permanent early-age reduction that costs tens of thousands of dollars over a long retirement.
Path 3: You Have Significant Supplemental Savings
When it applies: You have accumulated meaningful savings outside of TRS — in a 403(b), IRA, or other investment account.
What to consider: The sequencing of withdrawals matters as much as the amount saved. Drawing from the wrong account at the wrong time — especially during a market downturn — can permanently damage your long-term income. Understand how different account types are taxed and in what order withdrawals make the most sense.
What can go wrong: Over-withdrawing early in retirement and depleting accounts that were needed to cover costs in your 70s and 80s, when healthcare expenses are typically highest.
Path 4: You Are Single or Recently Widowed
When it applies: You do not have a spouse’s income to fall back on, or you have recently lost a spouse whose income contributed to household expenses.
What to consider: Your income plan must be entirely self-sufficient. Longevity risk is especially significant here, because there is no second income to absorb a shortfall if your savings run low. Healthcare cost planning is also critical, since there is no second insurance plan to share costs.
What can go wrong: Underestimating how long you will live and how much healthcare will cost in later years, leaving the income plan underfunded precisely when expenses are highest.
Path 5: You Have Limited Supplemental Savings and Depend Primarily on TRS
When it applies: Your retirement income will come almost entirely from your TRS pension, with little or no supplemental savings.
What to consider: Maximizing your TRS benefit becomes even more important. That means working as many years as possible before retiring, understanding whether service credit purchases make sense in your situation, and confirming the exact impact of your retirement date on your monthly benefit.
What can go wrong: Retiring earlier than necessary and locking in a lower benefit, then discovering years later that inflation has made that fixed income increasingly insufficient. Working with a retirement specialist who understands Texas TRS can help teachers in this situation identify options they may not have considered.
Quick Self-Check Before You Move Forward
Use these questions to identify gaps or uncertainty in your retirement plan before making decisions that are difficult to reverse.
- Do you know your TRS membership tier and exactly what retirement age and service credit combination qualifies you for an unreduced benefit? If not, your retirement date decision is based on incomplete information.
- Have you calculated the monthly gap between your projected TRS pension and your estimated monthly expenses in retirement? If you have not done this math, you do not yet know whether your pension is enough.
- Do you have a plan to cover healthcare costs between your retirement date and age 65? If you retire before Medicare eligibility and have no specific coverage plan, this gap can cost hundreds of dollars per month or more.
- Have you evaluated how long your supplemental savings need to last — and whether your current withdrawal strategy supports that timeline? A plan that works at 65 must also hold up at 85.
- If you qualify for Social Security benefits based on your own or a spouse’s work record, do you know how the repeal of WEP and GPO affects your projected benefit? This change may meaningfully alter your income picture and should be confirmed with SSA directly.
Why Gaps Often Go Undetected Until It’s Too Late
One of the most difficult aspects of retirement planning is that the most consequential decisions — annuity payment options, retirement dates, account withdrawal strategies — are made before the problems they cause become visible. A teacher who retires at 60 with a plan that looks adequate at the time may not feel the effects of inflation erosion until her mid-70s. A teacher who withdraws too aggressively from a 403(b) in the first five years of retirement may not exhaust those funds until her 80s — when working again is no longer realistic and expenses are highest.
The gap between when a retirement decision is made and when its consequences appear can be a decade or more. That delay creates a false sense of security. The income feels sufficient. The plan appears to be working. The warning signs are not yet visible.
By the time the shortfall becomes undeniable, the options available to correct it have narrowed considerably. That is why testing retirement assumptions before finalizing major decisions — not after — is the single most important step any Texas teacher can take to protect a long retirement.
Conclusion
The Texas TRS pension is a durable foundation — but it is not a complete retirement plan. Inflation, longevity, unplanned withdrawals, and gaps in supplemental income combine to create the financial pressure that causes teachers to run out of money in retirement. None of these risks are unpredictable, and none of them are unavoidable. They are, however, easy to underestimate when a retirement plan has never been tested against real numbers and real scenarios. The teachers who retire with financial security are rarely the ones who earned the most. They are the ones who understood the risks clearly enough to plan around them.